Every month, millions of Indians set aside a fixed amount for their goals through SIPs. In September 2026, that habit reached a new high. Monthly SIP inflows touched a record, even though the overall mutual fund industry saw a dip in assets. So what does this mean for you, and should it change how much you invest each month? Let’s look at the numbers in simple terms.
According to AMFI data for September 2026:
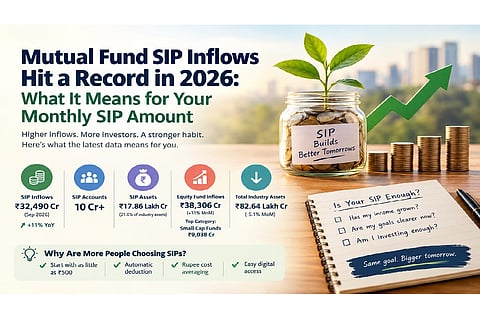
· Record SIP inflows: Investors put in ₹32,490 crore through SIPs, up from ₹32,297 crore in August.
· Year-on-year growth: This is about 11% higher than the ₹29,361 crore recorded in September 2025.
· SIP accounts: There were over 10 crore contributing SIP accounts.
· SIP assets: Money held through SIPs stood at ₹17.86 lakh crore, which is about 21.6% of the industry’s total assets.
· Equity funds: Equity mutual fund inflows rose about 31% to ₹38,306 crore. Small cap funds were the top category with ₹9,038 crore.
The industry’s total assets fell about 5.1% to ₹82.64 lakh crore in the same month. This drop came mainly from debt fund outflows and changes in the value of existing investments. Yet SIP money kept coming in, which shows how steady investors have become.
There are a few simple reasons.
Small starting amounts. You can start a SIP with as little as ₹500 a month, so it suits first-time investors and young earners.
Discipline without effort. The amount is deducted automatically each month, so you don’t need to decide when to invest.
No need to time the market. Markets move up and down. A SIP buys more units when prices are low and fewer when prices are high. This is called rupee cost averaging, and it smooths out your average cost over time.
Easy digital access. Investors can now start, pause or change a SIP from their phone within minutes.
A record number does not mean you must invest more right now. It tells you that many investors are staying invested through market ups and downs. That is a good habit to follow.
The amount of SIP you need depends on your personal income, objectives, and expenditure needs. But this can serve as a wake-up call to go through your own SIP. So ask yourself:
· Has my income grown since I started?
· Are my goals (a house, education, retirement) clearer now?
· Am I investing enough to reach them?
In case of an increase in salary, one’s SIP amount should also go up. There is a very basic principle adopted by many investors who put away a certain percentage of their earnings every year.
Here is an illustration with an assumed return of 12% a year. Actual returns are not guaranteed and will vary.
Notice how time does much of the work. The same ₹10,000 a month grows far more over 20 years than over 10. To try your own numbers, use the SIP calculator. Enter your monthly amount, expected return and time period to see an estimate in seconds.
1. Start with your goal. Decide how much money you need and by when. Then work backwards to the monthly amount.
2. Keep it comfortable. Choose an amount you can pay every month without stress. A SIP that you stop midway will not help you.
3. Increase it yearly. Even a 10% rise each year can raise your final corpus a lot. Many platforms offer a “step-up” option for this.
4. Match funds to your time frame. Equity funds suit long-term goals of five years or more. For shorter goals, you may prefer less volatile options.
5. Don’t stop in a falling market. Falls are when SIPs buy more units. Staying invested often works better than pausing.
6. Review once a year. Check whether your funds are doing as expected and whether your goals have changed.
You can compare options across categories on the mutual funds page before choosing where to invest.
According to the September 2026 figures, there has been an increase in Indian investors, who are investing on a regular monthly basis, irrespective of their sentiments towards the market. Your takeaway from this is clear – start investing early, invest consistently and increase your SIP according to your growing income. Estimate the amount you can invest through the SIP calculator, then look at mutual fund schemes available at 5paisa.
Disclaimer: This content is part of a marketing initiative.
